info@stockbinge.com.au
 03 8609 4895

Blog Details
- Home
- Blog Details
The Impact of Lithium Prices on ASX Battery Metal Stocks in 2026
Lithium prices have become one of the most important variables for Australia's battery-metal sector in 2026.
After a severe downturn, lithium prices rebounded strongly during the second half of 2025 and into 2026. The recovery has improved the operating environment for Australian lithium producers, but the market remains volatile. In June 2026, lithium carbonate prices fell sharply, demonstrating that the sector can still experience rapid price swings even after a strong recovery.
For investors researching ASX battery metal stocks, lithium prices can directly influence revenue, margins, cash flow, project economics and capital investment.
Companies such as Pilbara Minerals (ASX: PLS), Mineral Resources (ASX: MIN), Liontown Resources (ASX: LTR) and IGO (ASX: IGO) have different levels of lithium exposure and therefore different sensitivities to changes in lithium prices.
This article examines how lithium prices are affecting ASX battery metal stocks in 2026 and the key factors investors can monitor.
Lithium Prices and the ASX Battery Metal Sector in 2026
The lithium market entered 2026 after several difficult years.
The earlier lithium boom encouraged significant investment in new mines and processing capacity. As supply increased faster than demand, lithium prices fell sharply from their previous highs.
That downturn put pressure on producers, exploration companies and development projects.
The situation changed during 2025 and 2026.
According to Australia's Department of Industry, Science and Resources, lithium prices rebounded sharply from mid-2025 following supply disruptions in China and Zimbabwe combined with robust demand across the battery supply chain. The department expects spodumene and lithium hydroxide prices to remain elevated in the near term, although prices are projected to moderate from 2027.
This recovery has important implications for ASX battery metal stocks.
Why Lithium Prices Matter So Much for ASX Battery Metal Stocks
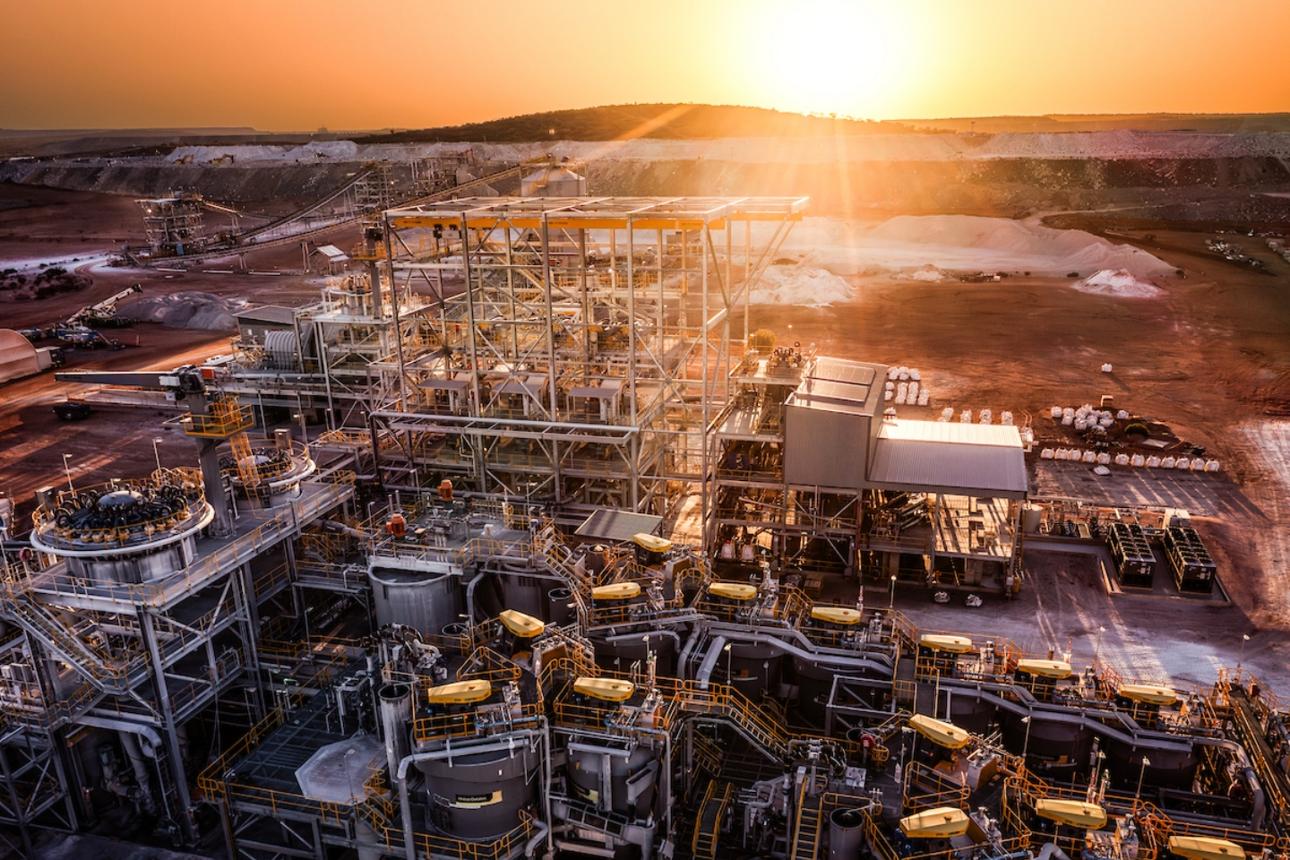
Lithium producers typically sell lithium-bearing products such as spodumene concentrate or refined lithium chemicals.
When prices increase, the revenue generated from each tonne of product can rise substantially, assuming production volumes and costs remain broadly stable.
This can improve:
- Revenue
- Operating margins
- EBITDA
- Free cash flow
- Balance-sheet strength
- Project economics
- Mine expansion opportunities
- Investor sentiment
The opposite can happen when lithium prices decline.
A lower realised price can compress margins, reduce cash generation and make higher-cost projects less attractive.
This is particularly important for companies still developing or ramping up major lithium mines.
Australian Lithium Outlook for 2026
Australia remains one of the world's major lithium-producing countries.
The Australian Government expects domestic mined and refined lithium production to grow during the outlook period. It projects Australian lithium export earnings to increase from approximately A$9.9 billion in 2025–26 to A$12.5 billion in 2026–27 in real terms.
However, supply growth remains an important consideration.
Global lithium demand is projected to grow by more than 11% annually through 2031, driven by electric vehicles and battery energy storage systems. Global supply is also projected to grow by approximately 10% annually.
This creates an important distinction for investors.
Higher demand does not automatically mean permanently higher lithium prices.
If supply expands sufficiently quickly, the market can remain balanced or oversupplied even while consumption grows.
Pilbara Minerals (ASX: PLS)
Pilbara Minerals is one of the most direct ways to examine the relationship between lithium prices and an Australian lithium producer.
Its Pilgangoora operation in Western Australia is a major hard-rock lithium asset.
The company's FY2026 results demonstrated the potential operating impact of stronger lithium-market conditions.
Pilbara Minerals reported 879.5kt of production and 891.6kt of sales in FY2026, both up 17%. Revenue reached approximately A$1.93 billion, while underlying EBITDA increased to approximately A$1.14 billion. The company finished FY2026 with approximately A$2.29 billion of cash.
The company also announced a fully franked final dividend of 5 cents per share.
Why Lithium Prices Matter to PLS
Pilbara Minerals' earnings are highly sensitive to realised spodumene pricing.
When lithium prices increase, the company can potentially generate significantly more cash from existing production.
That cash can then support:
- Expansion projects
- Processing improvements
- Balance-sheet strengthening
- Exploration
- Shareholder distributions
- Development of future assets
The opposite effect can occur during a lithium-price downturn.
This makes PLS an important stock for investors studying ASX battery metal stocks.
Mineral Resources (ASX: MIN)

Mineral Resources provides another example of how lithium prices interact with a diversified mining company.
The company has lithium exposure through operations including Wodgina and Mt Marion, while also having a substantial iron ore business.
This means its overall financial performance is not determined exclusively by lithium.
In its December 2025 quarter, MinRes reported attributable spodumene production of 138kt SC6 and sales of 143kt SC6. The average achieved price increased to approximately US$1,094 per dry metric tonne CIF SC6, representing a 29% increase from the previous quarter.
The company subsequently upgraded FY2026 lithium volume guidance for Wodgina and Mt Marion.
Why MIN Is Different
Compared with a pure-play lithium producer, Mineral Resources has greater exposure to multiple commodities.
That diversification can change the way lithium-price movements affect the overall company.
If lithium prices decline, the impact can be partly offset by performance from its iron ore operations.
However, investors still need to monitor the profitability and capital requirements of its lithium businesses separately.
Liontown Resources (ASX: LTR)

Liontown Resources offers another important case study because its Kathleen Valley lithium operation is still ramping up.
In its June 2026 quarterly report, Liontown reported 103,111 dry metric tonnes of spodumene concentrate production and 108,489 dry metric tonnes sold.
The company reported an average realised price of approximately US$1,880 per tonne on an SC6-equivalent basis during the quarter.
Liontown also reported A$137 million of net cash flow during the quarter and ended June with approximately A$561 million of cash.
Lithium Prices and Kathleen Valley
For a developing operation, lithium prices can have an especially important effect.
A higher realised price can improve cash generation while the mine is being ramped up.
A lower price can make it more difficult to absorb ramp-up costs and capital expenditure.
This means investors researching LTR need to consider two variables simultaneously:
Lithium price + operational execution.
A strong lithium market cannot compensate indefinitely for major production problems, while excellent operational execution cannot completely eliminate the effect of a severe commodity-price downturn.
IGO (ASX: IGO)
IGO provides another example of a more diversified battery-materials exposure.
The company has lithium exposure through its interest in Greenbushes and the Kwinana Lithium Hydroxide Refinery, alongside its nickel operations.
This creates a different risk profile from a pure-play lithium producer.
Lithium prices remain important to the company's earnings, but investors also need to monitor nickel-market conditions and the performance of its downstream processing operations.
The broader lesson is that ASX battery metal stocks should not be treated as a single homogeneous group.

Each company's sensitivity to lithium prices depends on:
- Ownership percentage
- Product type
- Realised pricing
- Production volume
- Operating costs
- Processing exposure
- Debt
- Capital expenditure
- Other commodities
Lithium Price Recovery Does Not Remove Supply Risk
One of the most important considerations for 2026 is that higher lithium prices can encourage new supply.
This creates a potential feedback loop.
Higher lithium prices → stronger producer cash flow → more investment → additional supply → potential future price pressure.
The Australian Government expects global lithium supply to grow at roughly 10% annually through 2031, compared with demand growth of more than 11%. It expects the market to remain oversupplied early in the outlook before moving back toward balance by 2030.
Therefore, investors need to distinguish between a short-term price recovery and a sustained structural shortage.
Electric Vehicles Remain a Major Demand Driver
Electric vehicles remain one of the most important sources of lithium demand.
Lithium-ion batteries require lithium compounds in their cathode and electrolyte supply chains, making EV adoption a major driver of long-term lithium consumption.
However, battery technology continues to evolve.
Changes in battery chemistry, improvements in energy density, recycling and alternative technologies can all affect future lithium intensity.
Investors therefore need to monitor not only EV sales but also the amount of lithium required per unit of battery capacity.
Battery Energy Storage Is Becoming More Important
Electric vehicles are not the only source of lithium demand.
Battery energy storage systems are becoming increasingly important as electricity grids incorporate more renewable generation.
The Australian Government specifically identifies both EV adoption and battery energy storage deployment as major drivers of projected global lithium demand.
This provides another potential source of demand beyond passenger vehicles.
For Australian producers, stronger global storage demand could support lithium consumption even if EV growth rates vary between markets.
Lithium Prices Can Affect ASX Valuations
Commodity prices can influence mining-company valuations through expected future cash flow.
Suppose a lithium producer sells a fixed amount of concentrate.
A higher realised lithium price can increase expected revenue, assuming production and costs remain unchanged.
That can potentially improve:
- EBITDA expectations
- Free-cash-flow forecasts
- Project valuations
- Balance-sheet forecasts
- Market sentiment
But investors should avoid treating a higher lithium price as a direct one-for-one increase in company value.
Mining companies also face:
- Royalties
- Processing costs
- Labour costs
- Energy costs
- Freight
- Sustaining capital expenditure
- Expansion capital expenditure
- Taxes
- Financing costs
The actual effect of a lithium-price change therefore depends on the company's cost structure.
The Importance of Operating Costs
Cost position can become especially important during a lithium downturn.
A low-cost producer may remain cash-flow positive at prices where a higher-cost operation becomes marginal.
This is why investors should examine metrics such as:
- Cash cost per tonne
- AISC where applicable
- Processing costs
- Mining costs
- Unit operating costs
- Sustaining capital
- Expansion capital
For example, Pilbara Minerals' stronger FY2026 financial performance was supported not only by improved pricing but also by higher production and disciplined cost management.
Lithium Price Volatility Remains a Major Risk
The 2026 lithium market has demonstrated that a recovery does not necessarily mean a smooth upward trend.
Morningstar reported that lithium carbonate fell by roughly 20% in June 2026, while another market analysis reported a roughly 12% June decline in spodumene prices.
The exact price movement differs depending on the lithium product and benchmark being measured, but the broader message is consistent:
Lithium remains a highly volatile commodity market.
That volatility can flow directly into ASX lithium and battery-metal shares.
Comparing Selected ASX Battery Metal Stocks
| Company | ASX Code | Main Battery-Metal Exposure | Other Major Exposure | Lithium Price Sensitivity |
|---|---|---|---|---|
| Pilbara Minerals | PLS | Spodumene/lithium | Primarily lithium-focused | High |
| Mineral Resources | MIN | Lithium | Iron ore | Moderate to high |
| Liontown Resources | LTR | Spodumene/lithium | Primarily lithium-focused | High |
| IGO | IGO | Lithium | Nickel | Moderate to high |
This is not an investment ranking.
Instead, it demonstrates how lithium-price exposure differs between companies.
What Investors Should Watch in 2026
Investors researching ASX battery metal stocks can monitor several indicators throughout 2026.
1. Spodumene Prices
Australian producers selling spodumene concentrate are directly exposed to changes in realised concentrate pricing.
2. Lithium Carbonate and Hydroxide Prices
Refined lithium products provide additional information about downstream market conditions.
3. Chinese Battery Demand
China remains a major part of the global battery supply chain.
Changes in EV production, battery manufacturing and energy-storage deployment can affect lithium consumption.
4. EV Sales
Global electric-vehicle growth remains an important long-term demand indicator.
5. Battery Storage Deployment
Rapid growth in grid-scale storage could create additional lithium demand.
6. New Mine Supply
New projects and mine restarts can increase supply and place downward pressure on prices.
7. Inventory Levels
Changes in lithium inventories can provide clues about short-term market balance.
8. Company Costs
A higher lithium price is more valuable to a producer with a competitive cost base.
9. Capital Expenditure
Investors should examine whether companies are using improved cash flow for productive investment, balance-sheet strengthening or other purposes.
10. Production Guidance
Actual production compared with guidance can reveal whether a company is successfully executing its operating plan.
The Difference Between Lithium Producers and Developers
Not every lithium stock benefits equally from a lithium-price recovery.
An established producer already generating revenue can potentially benefit from higher realised prices relatively quickly.
A developer still building a project may benefit through improved project economics and financing conditions, but it may not generate meaningful operating cash flow until production begins.
This distinction is particularly important when comparing established producers such as Pilbara Minerals with companies still progressing major development projects.
Could Higher Lithium Prices Last?
The answer depends on the balance between supply and demand.
The Australian Government's 2026 outlook provides a relatively constructive near-term picture, with prices expected to remain elevated in the short term and Australian lithium export earnings forecast to rise in 2026–27. However, it also expects lithium prices to moderate from 2027 as supply expands.
That creates two separate questions for investors.
Near term: Can stronger demand and supply disruptions keep lithium prices elevated?
Long term: Can demand growth from EVs and energy storage absorb the substantial amount of new production entering the market?
The answers could have very different implications for ASX battery-metal companies.
How Lithium Prices Could Affect ASX Battery Metal Stocks
The relationship can be simplified into four stages:
Lithium prices rise
↓
Producer realised prices increase
↓
Revenue and margins potentially improve
↓
Cash flow and project economics potentially strengthen
The reverse can happen during a downturn.
However, the actual impact varies significantly by company.
A producer with low costs, strong production and a healthy balance sheet may be able to withstand weaker prices more effectively than a highly leveraged developer with substantial future capital requirements.
Key Risks for ASX Battery Metal Investors
Commodity Price Risk
Lithium prices can change rapidly.
Supply Growth
New mines and restarted capacity can increase global supply.
Technology Risk
Battery chemistry and recycling developments could change lithium demand intensity.
Project Execution Risk
New mines can experience construction delays, cost overruns or slower-than-expected ramp-ups.
Financing Risk
Developers may require significant capital before generating operating cash flow.
Currency Risk
Australian producers selling into international markets can be affected by movements in the Australian dollar.
China Exposure
Changes in Chinese battery manufacturing, EV demand and policy can influence the global lithium market.
Conclusion
The impact of lithium prices on ASX battery metal stocks in 2026 is significant because Australian producers are directly exposed to changes in the global lithium market.
The recovery in lithium prices from the lows of 2025 has improved conditions for producers. Australia's Department of Industry expects lithium export earnings to rise from A$9.9 billion in 2025–26 to A$12.5 billion in 2026–27, while global lithium demand is projected to grow by more than 11% annually through 2031.
Pilbara Minerals has already demonstrated the potential financial impact of stronger market conditions, reporting record FY2026 production and sales alongside A$1.93 billion of revenue and A$1.14 billion of underlying EBITDA.
However, lithium remains a cyclical and volatile commodity.
The sharp price movements seen during 2026 demonstrate why investors should not assume that a lithium recovery will continue in a straight line. At the same time, projected growth in EVs and battery energy storage provides important long-term demand support.
For investors researching ASX battery metal stocks, the most important factors to monitor are therefore lithium prices, supply growth, demand trends, production costs, project execution, balance-sheet strength and free cash flow.
The companies that can maintain competitive costs and strong operating performance through different stages of the lithium cycle may have very different financial outcomes from companies that depend on persistently high commodity prices.
Frequently Asked Questions
Why are lithium prices important for ASX battery metal stocks?
Lithium prices directly influence the revenue and margins of lithium producers. Changes in realised prices can therefore affect cash flow, project economics, earnings expectations and investor sentiment.
Which ASX stocks are most exposed to lithium prices?
Pilbara Minerals and Liontown Resources have relatively direct lithium exposure, while Mineral Resources and IGO have more diversified commodity or processing exposure.
Are lithium prices rising in 2026?
Lithium prices rebounded strongly from mid-2025, although prices have remained volatile during 2026. Australia's Department of Industry expects near-term prices to remain elevated before moderating from 2027.
What drives lithium demand?
Electric vehicles and battery energy storage systems are major sources of lithium demand. Industrial applications and other battery uses also contribute to consumption.
What could cause lithium prices to fall?
Potential factors include additional mine supply, weaker-than-expected EV demand, changes in battery technology, inventory accumulation and slower global economic activity.
Are all ASX battery metal stocks equally affected by lithium prices?
No. Companies differ in their lithium exposure, production costs, ownership interests, product mix, project stage, debt and exposure to other commodities.
What should investors monitor besides lithium prices?
Production volumes, realised pricing, unit costs, free cash flow, capital expenditure, balance-sheet strength, project guidance, inventories and global supply-demand forecasts can all provide useful context.
Financial Disclaimer: This article is for general information and educational purposes only and does not constitute personal financial advice or a recommendation to buy or sell any security. Commodity prices and mining-company earnings can be highly volatile. Investors should conduct their own research and consider their individual circumstances before making investment decisions.
Talk to Our Experts
ABN 54 672 177 347 | ACN 672 177 347
Copyright © 2026 StockBinge. All Right Reserved. Design by StockBinge.